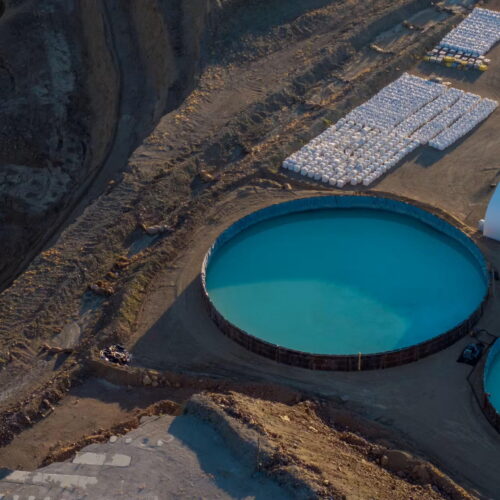
Decades of cheaper imports and environmental hurdles left the United States heavily dependent on China for crucial rare earth processing. Now, Washington is scrambling to rebuild a domestic supply chain facing massive technological and engineering deficits.
By Nexvoro Tech Wire
PUBLISHED WED, SEP 23, 2026 4:14 PM UTC • 7 MIN READ
The Ubiquitous Power of Rare Earth Elements
Look around you, and you will see rare earth elements at work in nearly every facet of modern daily life. A smartphone vibrates because a specialized magnet moves an internal weight, while its display screen was meticulously polished with cerium powder. Furthermore, its digital connection to the rest of the world crosses vast oceans on fiber-optic cables amplified with erbium. If you drove a vehicle today, a powerful rare earth magnet helped power your steering mechanism, while a cerium compound actively scrubbed the vehicle's exhaust emissions.
All of these indispensable consumer and industrial devices function because of 17 distinct metals collectively known as rare earth elements. Ironically, the scientists who gave the group that designation back in 1794 created a scientific misnomer. Cerium alone, for instance, is actually about as common in the Earth's crust as copper. However, separating rare earth minerals cleanly from one another and extracting them from raw ore is an intensely difficult, chemically complex endeavor.
As a direct result of these complex refining hurdles, nations that control the processing of rare earth minerals wield immense geopolitical and economic leverage. China currently processes the vast majority of the rare earth minerals used around the world. Crucially, it is not just consumer electronics that depend heavily on these Chinese exports; the United States military's advanced F-35 fighter jets and Virginia-class nuclear submarines rely heavily on rare earths to operate effectively.
Strategic Vulnerabilities and Geopolitical Leverage
Drawing from years of personal experience adjudicating complex war games for the US Navy, the underlying reality of these material dependencies becomes starkly clear. War games force participants to identify the hidden constraints that can render an otherwise beautiful tactical plan completely untenable. Rare earth processing bottlenecks represent exactly such a critical constraint in modern national security planning.
China vividly showcased the immense power of its rare earths leverage through a series of stringent export controls issued in 2025. Although Beijing subsequently agreed to suspend those specific controls - at least until November 10, 2026 - the underlying strategic dynamic remains unchanged. Controlling the global supply enables a government to deliberately slow a rival nation's technological growth, or halt it altogether.
China's ability to extend the suspension of its export controls or let them go into effect at will grants Beijing profound leverage on the global stage. In the classic parlance of Theodore Roosevelt's foreign policy doctrine, this industrial dominance operates as a very big stick. Global competitors are left walking softly while navigating a supply chain dictated almost entirely by Beijing's regulatory whims.
The Decline of Domestic Production and the Rise of China
California's historic Mountain Pass mine famously led world production of rare earths until the late 1980s. However, multiple instances of radioactive wastewater spilling from the active mine site out into the Mojave Desert made it extraordinarily difficult to keep domestic production running smoothly under mounting environmental scrutiny.
When China aggressively expanded its own domestic mining operations and subsequently sold the processed materials globally for far less, the economic logic of switching rare earth suppliers was simple for Western manufacturers. Consequently, the Mountain Pass separation plant closed its doors in 1998, and the mine itself halted all operations altogether in 2002.
Although MP Materials successfully restarted mining operations at Mountain Pass in 2017 as growing concern over critical mineral access mounted, the United States still imported more than two-thirds of the rare earth elements it consumed as recently as 2025. Meanwhile, China mined roughly 60 percent of the world's rare earth elements used specifically in permanent magnets in 2024, and handled an astounding 91 percent of global separation and refining.
The Steep Cost of Rebuilding the US Supply Chain
Buyers utilizing processing capabilities located in China acquired raw materials well below the cost of manufacturing them domestically, while successfully avoiding all domestic cleanup bills and negative press. Yet, in doing so, Western industries ceded vital strategic leverage to foreign processors in exchange for short-term cost savings. The trade was fully understood at the time; it simply did not look threatening from a China that was still rising.
Rebuilding this lost industrial capacity is a monumental challenge. The US Government Accountability Office cited estimates back in 2010 that completely rebuilding a domestic supply chain - inclusive of mining, chemical separation, and magnet manufacturing - would take as long as 15 years. Actual efforts to rebuild that critical infrastructure have proven notoriously slow for several compounding reasons.
China currently runs its advanced processing plants with thousands of highly experienced chemical and metallurgical engineers, whereas the United States possesses far fewer domestic experts. Furthermore, today's industrial-scale, cutting-edge refining technologies were developed primarily within China, and Beijing has zero economic or strategic incentive to share them. Highlighting this protective stance, Beijing officially banned exports of the core separation technology itself in December 2023.
Federal Investments and the Path Forward to 2028
Recognizing the acute national security risk, the US government has committed more than $7 billion since April 2025 in an aggressive bid to rebuild domestic rare earth production capacity from the ground up. As part of this sweeping federal push, the Pentagon purchased $400 million of preferred stock in rare earth producer MP Materials in 2025, securing a vital 15 percent ownership stake in the enterprise.
Market watchers and defense officials are closely monitoring operational timelines as domestic players attempt to scale up. MP Materials currently expects its next major magnet manufacturing facility to begin rigorous testing of its advanced production equipment by 2028.
Until these domestic facilities come fully online at scale, American manufacturing and defense supply chains remain tethered to an intricate global market dominated by a single geopolitical competitor. The race to achieve resource independence is arguably the most critical industrial policy challenge facing Washington today.
Reporting synthesized under Nexvoro.tech Editorial Standards • Referenced via Ars Technica
Verified Dispatch